Discover how business interruption insurance can act as a financial safety net for your company when disaster strikes and operations are forced to stop.
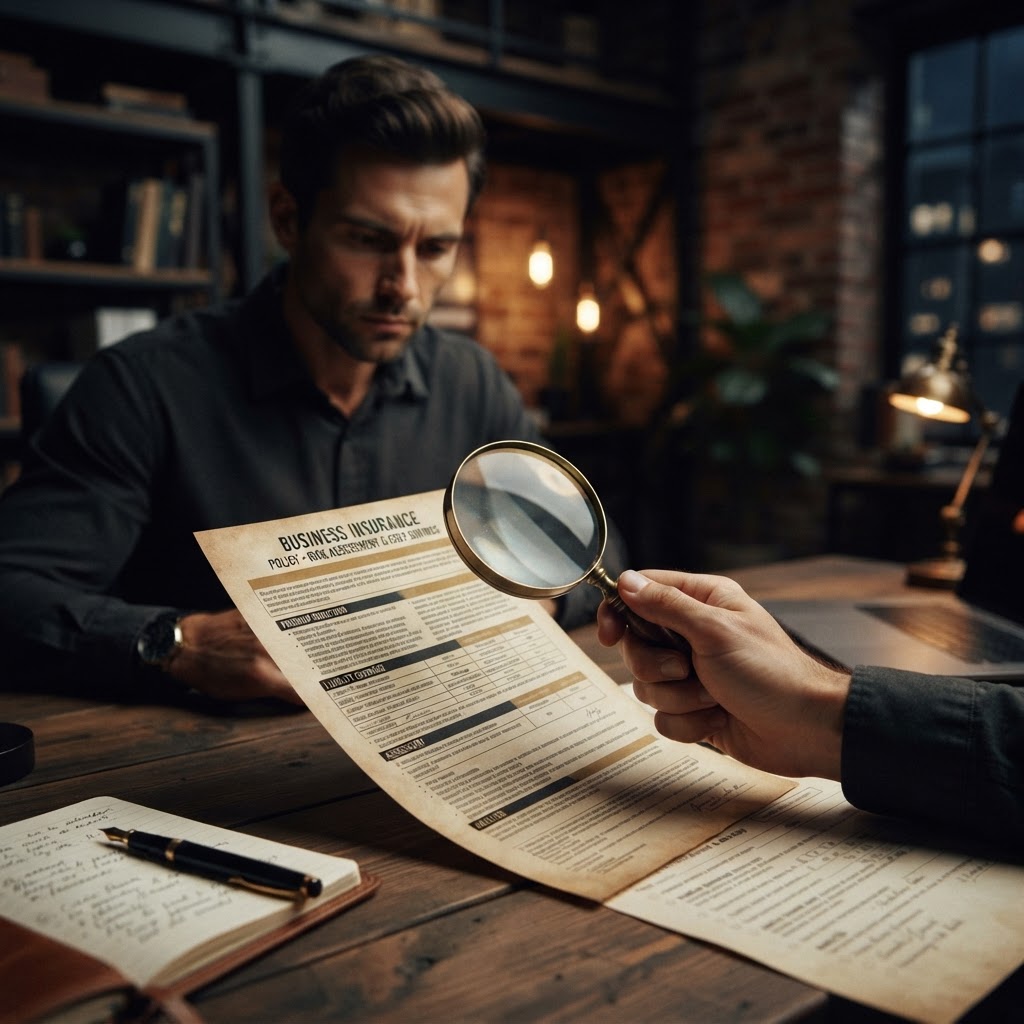
What Is Business Interruption Insurance? Business interruption insurance, often referred to as business income coverage, is a specific type of commercial insurance designed to replace lost income when your business is forced to cease operations due to a covered peril. It acts as a bridge, helping you maintain financial stability while you work to get your doors back open. While many owners focus solely on property damage, the reality is that the loss of income following an event is often more devastating to a company's longevity than the cost of repairs themselves. ## What Exactly Does It Cover? This coverage is designed to mimic the financial position your business would have been in had the loss not occurred. It typically covers net income (based on your financial records), necessary continuing expenses, such as rent and taxes, and payroll for essential employees. It may also cover extra expenses incurred to mitigate your losses, such as the costs of moving into a temporary location or renting equipment to maintain limited operations. ## Triggering Your Policy: How It Works It is critical to understand that this insurance is not a general loss-of-profit policy. It is almost always tied to your commercial property insurance policy. This means that for a claim to be triggered, there must be physical damage to your property—such as a fire, storm, or burst pipe—that causes a total or partial shutdown of your business operations. It does not typically cover business downturns caused by economic shifts or market changes. ## The Importance of the Period of Restoration The 'period of restoration' is the length of time your policy covers during a shutdown. It begins on the date of the direct physical loss and ends when your property should be reasonably repaired, rebuilt, or replaced. Owners must be careful here; if you do not have adequate coverage limits to cover an extended period of downtime, you could be left footing the bill while waiting for materials or contractors. ## Common Misconceptions to Avoid One of the most dangerous myths is that business interruption insurance covers pandemics or viral outbreaks. Historically, most standard policies have specific exclusions for communicable diseases. Another mistake is underestimating the amount of coverage needed. To calculate your needs, review your net income plus continuing operating expenses from the previous 12 months, and then project growth for the next year. You want to ensure you have enough 'limit' to survive a worst-case scenario. ## How to Prepare Today As an independent agency operating in all 50 states, we recommend that you conduct a thorough audit of your current policy. Review your declarations page to see if you have business income coverage, and if so, what the limits are. Maintain updated financial statements and tax records off-site or in the cloud. Having clear documentation will dramatically speed up the claims process if you ever need to use it. If you are unsure about your current protection, reach out to an advisor to discuss a custom gap analysis.
Business InterruptionCommercial InsuranceSmall BusinessRisk ManagementFinancial Protection
Have questions about your coverage?
Our team shops top-rated carriers to find the right protection for your business — at the right price.
Get a Free Quote